 Bullish Portfolio
Introduction to AI in Modern Risk Budgeting
In 2026, portfolio managers face unprecedented volatility driven by geopolitical shifts, technological disruption, and evolving macroeconomic policies. Traditional risk budgeting methods often fall short in adapting quickly enough. AI-optimized risk budgeting leverages machine learning to dynamically allocate risk across assets, improving diversification and returns while controlling downside exposure. This evolution is particularly critical as markets experience rapid correlation shifts that static models struggle to capture in real time.
This approach integrates optimization algorithms with real-time data feeds, enabling portfolios to respond to correlation breakdowns faster than static models allow. Professional managers are increasingly adopting these techniques to meet client mandates in uncertain environments. By processing vast datasets from multiple sources, AI systems identify subtle patterns that human analysts might overlook, leading to more resilient portfolio structures across equities, fixed income, and commodities.
Traditional Risk Budgeting vs. AI-Driven Approaches
Conventional risk budgeting relies on historical volatility estimates, fixed correlation matrices, and periodic rebalancing. These methods assume relatively stable market regimes, which rarely hold in 2026. In contrast, AI-driven systems use neural networks and reinforcement learning to process live market signals, detect regime changes, and adjust risk budgets continuously. The result is a more proactive stance that anticipates rather than reacts to market stress events.
Key differences include speed of adaptation and granularity of analysis. Traditional models might rebalance monthly; AI versions can recalibrate daily or intraday based on incoming data streams. This leads to tighter control over tail risks and better capital efficiency. Managers comparing the two often note that AI approaches reduce the lag between signal detection and action, which can preserve capital during sudden downturns. For instance, during equity market swings, traditional methods may maintain outdated risk budgets while AI reallocates within hours.
Core AI Techniques for Enhanced Risk Management
Optimization Algorithms
Advanced techniques such as genetic algorithms and stochastic gradient descent optimize risk contributions across thousands of variables simultaneously. These replace mean-variance optimization with more robust objectives that account for non-normal distributions and fat tails common in today's markets. Portfolio managers can layer constraints for liquidity, regulatory limits, and client-specific mandates directly into the objective function.
Real-Time Correlation Analysis
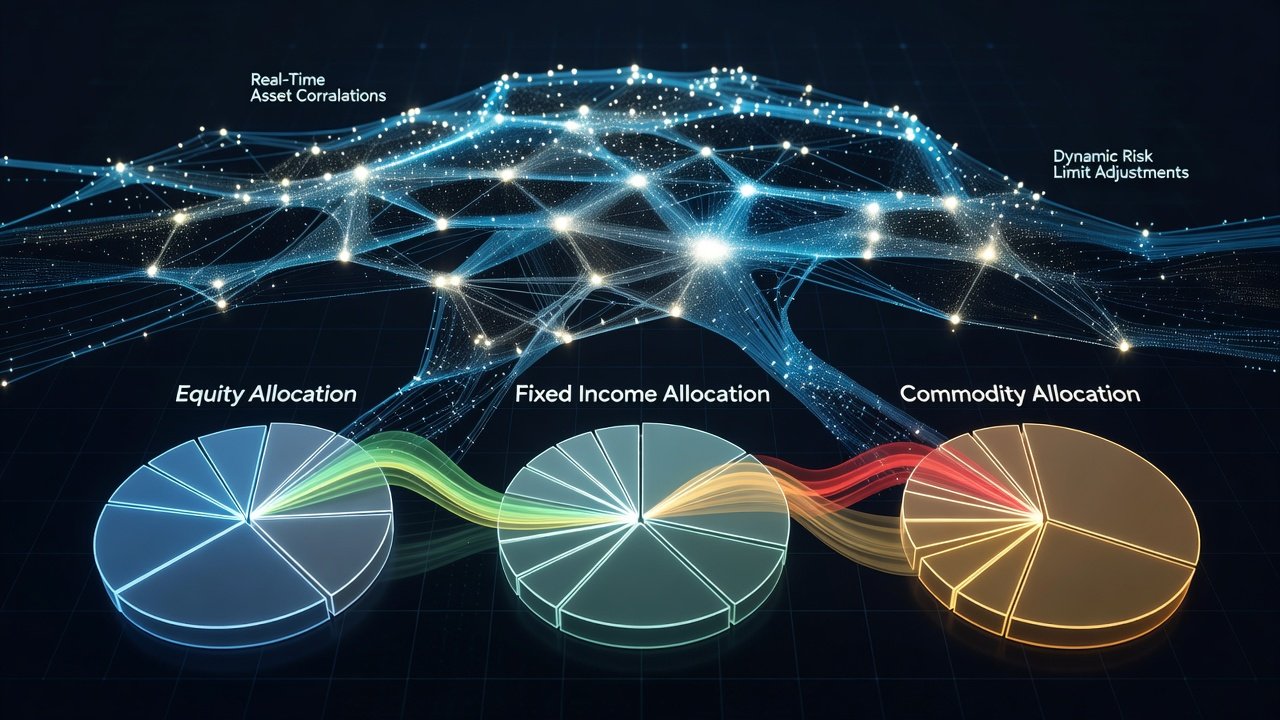
Machine learning models continuously monitor pairwise and higher-order correlations using techniques like dynamic conditional correlation (DCC) GARCH combined with deep learning. When correlations spike unexpectedly, the system automatically reduces exposure to clustered risks. This real-time capability proves especially valuable in cross-asset portfolios where equity and commodity correlations can shift rapidly due to external shocks.
Dynamic Risk Limits
AI sets and adjusts risk limits in real time using reinforcement learning agents trained on historical stress scenarios. Limits on value-at-risk or expected shortfall adapt based on current liquidity conditions and volatility regimes. Bank for International Settlements research highlights the importance of adaptive frameworks in maintaining systemic stability.
Practical Examples Across Asset Classes
Consider an equity allocation where AI identifies sector-specific volatility clustering and reallocates risk budgets toward defensive factors such as utilities or healthcare. In fixed income, models detect yield curve steepening signals early, shifting duration exposure dynamically to protect against rate volatility. For commodities, real-time analysis of supply-chain data and weather patterns helps balance energy and agricultural risk contributions more effectively than quarterly reviews allow.
Another detailed example involves a multi-asset portfolio with 40 percent equities, 35 percent fixed income, and 25 percent commodities. An AI system might detect an emerging correlation between oil prices and high-yield bonds during a supply disruption. It then reduces commodity risk budgets while increasing allocations to inflation-protected securities, all while maintaining overall portfolio volatility targets. These adjustments occur without waiting for end-of-day reports.
Implementation Steps for Portfolio Managers
- Integrate high-quality alternative data sources with existing portfolio systems, ensuring clean pipelines from market feeds and news sentiment indicators.
- Train models on both historical and forward-looking stress scenarios, including synthetic data generation to simulate rare events.
- Establish governance frameworks that include human oversight of AI recommendations, with clear escalation protocols for unusual outputs.
- Conduct backtesting across multiple market regimes before live deployment, measuring performance against benchmarks like maximum drawdown and Sharpe ratio improvements.
- Monitor key performance indicators such as risk-adjusted returns and drawdown frequency post-implementation, with weekly review meetings involving quantitative and fundamental teams.
Recommended Tools and Potential Pitfalls
Leading platforms include those from established providers offering API access to machine learning risk engines. Managers should watch for pitfalls such as model overfitting, data quality issues, and regulatory scrutiny around algorithmic decision-making. U.S. Securities and Exchange Commission guidelines emphasize transparency in automated investment processes. Additional pitfalls include over-reliance on black-box outputs and failure to account for transaction costs in high-frequency rebalancing scenarios. Regular audits and explainability requirements help mitigate these risks.
Measurable outcomes reported by early adopters include improved Sharpe ratios and reduced maximum drawdowns during volatile periods, particularly when combining AI signals with traditional oversight. Teams that implement phased rollouts often see faster adoption and fewer operational disruptions.
Conclusion
AI-optimized risk budgeting represents a significant evolution for 2026 portfolio construction. By combining sophisticated algorithms with real-time insights, managers can achieve superior diversification and resilience. Successful adoption requires careful planning, robust infrastructure, and ongoing validation to ensure alignment with fiduciary responsibilities.
FAQ: Integrating AI Risk Budgeting into Existing Workflows
How long does initial model training typically take? Most institutions complete foundational training within 4-8 weeks when leveraging pre-built frameworks and cloud resources.
What data infrastructure is required? High-frequency market data, alternative datasets, and scalable cloud compute resources are essential starting points for reliable performance.
Can smaller teams adopt these methods? Yes, through managed AI services and modular platforms that reduce the need for in-house data science expertise while still delivering meaningful improvements.
How do regulators view AI-driven allocations? Oversight focuses on transparency and risk controls; documentation of model logic remains critical for compliance as outlined by bodies like the Federal Reserve.
What training do portfolio managers need? Basic understanding of machine learning concepts combined with domain expertise allows effective collaboration with data scientists during implementation.
How frequently should models be retrained? Quarterly retraining is common, with continuous monitoring for concept drift that may trigger earlier updates during regime shifts.
No comments yet. Be the first!